How to Read Your County’s Wildfire Risk Map (And What to Do With That Information)
Wildfire risk maps can feel like a verdict. They’re not. Here’s how to read your county’s map correctly, understand what “high risk” actually means, and turn that information into practical, layered preparation for your home and evacuation plan.
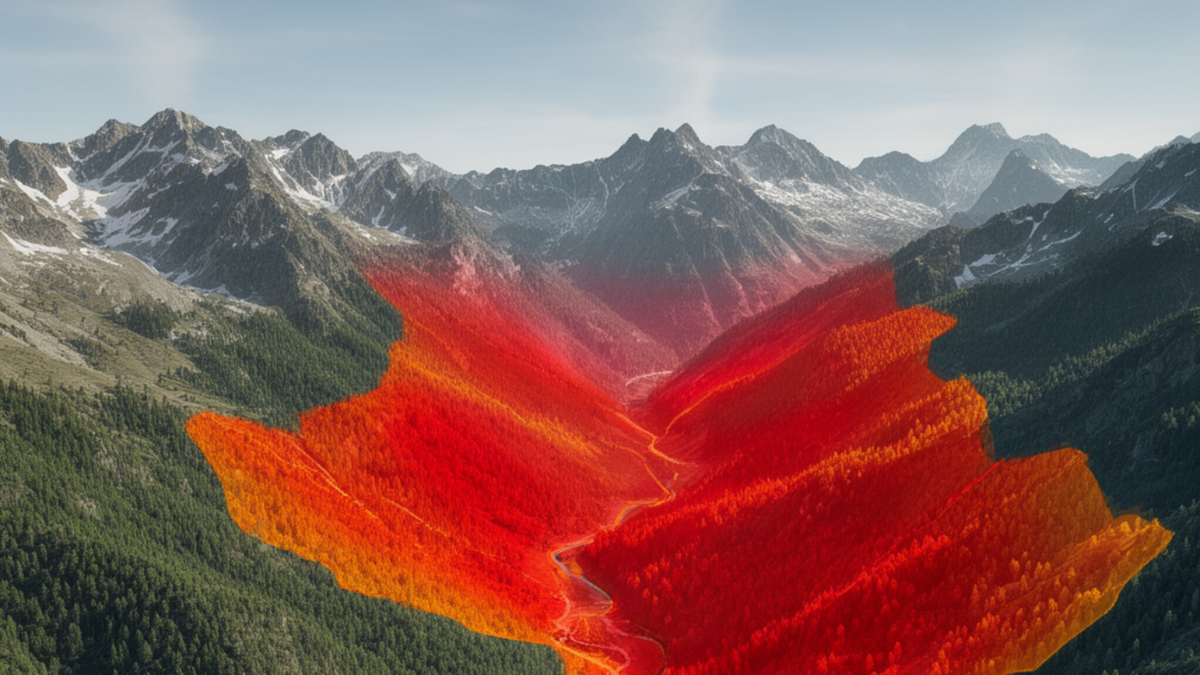
Wildfire risk maps can feel like a verdict.
You type in your address. A color appears. Maybe it says “High” or “Very High.” And suddenly it feels like the house you worked for is sitting in a danger zone.
But a wildfire risk map is not a prediction. It’s a planning tool. The goal isn’t to scare you. It’s to help you understand what kind of risk you live with — and what actions actually matter in response.
This guide will help you read your county’s wildfire risk map clearly and use it to make practical decisions.
FACING A NON-RENEWAL
OR RATE SPIKE?
Get a personalized home insurance quote from our partner Five Bays Insurance Agency to make sure you’re not paying more than you should.
Key Takeaways
- A wildfire risk map shows probability and exposure, not whether your home will burn.
- “High” risk usually reflects vegetation, wind patterns, and topography — not the condition of your specific house.
- Most homes are lost to wind-driven embers, not a wall of flames.
- Your preparation strategy should match your risk level — layered and realistic.
- The map is information. Your response is what changes outcomes.
What Wildfire Risk Maps Actually Measure
County and state wildfire hazard maps are typically based on three primary factors: vegetation (fuel), topography, and weather patterns. Analysts evaluate how dense and combustible the surrounding vegetation is, how steep the terrain might accelerate fire spread, and how wind historically behaves in that region. From there, they estimate potential fire intensity and the likelihood of rapid spread.
What these maps do not measure is just as important.
They do not account for whether your roof is Class A rated. They do not reflect whether you have ember-resistant 1/8-inch metal mesh over your vents. They don’t consider whether you’ve replaced wood mulch in the 0–5 foot zone with gravel, or whether your eaves are boxed in. In other words, they evaluate area-wide hazard, not individual mitigation.
That distinction matters because environmental hazard and structural vulnerability are related but separate issues. Two homes sitting side by side in a “Very High” zone may perform very differently depending on how they are maintained and hardened.
Why “High Risk” Does Not Mean “Inevitable Loss”
Seeing a high-risk designation often leads people to assume that home loss is only a matter of time. In reality, wildfire behavior is more nuanced.
Most structure loss during wildfires is ember-driven. When wind pushes a fire front forward, it sends burning embers far ahead of the flames — sometimes more than a mile. These embers accumulate in vulnerable areas: roof valleys filled with debris, gutters packed with dry leaves, unscreened attic vents, mulch beds touching siding, wooden fencing attached directly to the house. Homes frequently ignite without ever being touched by a wall of flame.
The immediate area closest to the house — particularly the first five feet — plays an outsized role in ignition risk. Combustible landscaping, stacked firewood, decorative bark mulch, or stored materials in this zone create opportunities for embers to turn into structure fires.
Risk maps do not capture these details. They tell you the environment has the potential to produce intense fire behavior. They do not determine whether your home will withstand ember exposure.
How to Translate Map Categories Into Action
Rather than asking whether the map label is good or bad, a more productive question is: “What level of preparation does this environment require?”
Here is how to think about it practically.
If You’re in a Moderate Zone
Moderate zones still experience wildfire. They simply tend to have lower predicted fire intensity or slower spread under modeled conditions. The mistake homeowners often make here is assuming preparation isn’t necessary.
Even in moderate areas, wind-driven ember events can occur. Simple, relatively low-cost steps often provide significant protection: cleaning gutters regularly, installing 1/8-inch metal mesh over attic and foundation vents, removing combustible material within five feet of the home, and maintaining a basic evacuation go-bag. Preparation in these zones is usually manageable and highly effective.
If You’re in a High Zone
High zones indicate stronger potential fire behavior due to terrain, fuel, and wind patterns. Ember exposure is more likely, and fire spread may be faster.
A common mistake in high zones is focusing exclusively on clearing distant brush while neglecting the structure itself. Vegetation management matters, but home hardening is often more critical. Upgrading vents, maintaining a noncombustible 0–5 foot zone, ensuring roofing materials meet Class A standards (especially if replacement is already planned), and reviewing evacuation routes become more important.
Insurance literacy also becomes more relevant in these areas. Understanding dwelling limits, replacement cost estimates, and documentation practices can reduce financial uncertainty if a loss occurs.
If You’re in a Very High or Extreme Zone
In very high or extreme zones, modeled fire intensity and ember exposure can be significant, especially under wind-driven conditions.
Here, preparation needs to be layered. Ember-resistant venting, strict maintenance of the immediate zone, evaluation of decks and attached fences, and ongoing roof and gutter maintenance are foundational. Evacuation planning carries equal weight. Identifying multiple routes, keeping vehicles fueled during peak fire season, and establishing personal trigger points for leaving before mandatory orders are issued can reduce risk during fast-moving events.
At this level, it is also worth reviewing insurance coverage annually and ensuring documentation of home condition and contents is current.
What Wildfire Risk Maps Don’t Show
Risk maps do not reflect evacuation bottlenecks, road width limitations, bridge access, or how quickly local alert systems operate. They do not measure neighborhood-level defensible space compliance or infrastructure resilience, such as underground utilities versus overhead power lines.
You could live in a moderate zone with limited evacuation routes, or in a very high zone with strong community-level mitigation and excellent access. The map is one piece of a broader risk picture.
Tradeoffs and Real-World Constraints
Comprehensive wildfire retrofits can be expensive. Not everyone can replace siding, upgrade windows, or install a new roof immediately. Preparation should account for cost and timing realities.
The highest-impact steps are often incremental: clearing the immediate five-foot zone, installing proper vent screening, sealing gaps where embers can enter, and maintaining roofs and gutters. These are manageable improvements that meaningfully reduce vulnerability without requiring a full renovation.
Preparation reduces risk; it does not eliminate it. That is an honest but important reality. The goal is not invulnerability. It is resilience.
Common Misconceptions About Wildfire Risk Maps
One common misconception is that a high-risk designation guarantees loss. It does not. Many homes in high-hazard zones survive because they are hardened and maintained.
Another misconception is that a lower-risk designation removes the need for preparation. Ember events do not stop at map boundaries, and changing climate patterns continue to alter fire behavior in many regions.
Finally, there is a tendency to assume insurance will resolve everything after a loss. Insurance can provide financial support, but it does not address evacuation risk, rebuilding delays, or emotional and logistical disruption.
Where to Start Today
If you’ve recently checked your address and feel unsettled, begin with something concrete and manageable. Walk the perimeter of your home and look closely at the first five feet. Remove anything combustible touching the structure. Check your attic and foundation vents for proper metal mesh screening. Identify at least two evacuation routes and write them down.
You do not need to overhaul your property overnight. Wildfire risk is a long-term condition in many areas, and preparation works best when it is layered and sustained over time.
The map gives you context. Your actions determine how exposed your home truly is.
Related Articles
- The Ultimate Emergency Kit List for Your Car
- The Only Emergency Kit Checklist PDF You Need
- The Essential Go Bag for Family Checklist
FACING A NON-RENEWAL
OR RATE SPIKE?
Get a personalized home insurance quote from our partner Five Bays Insurance Agency to make sure you’re not paying more than you should.
Frequently Asked Questions
Do wildfire risk maps affect insurance rates? They often influence underwriting decisions, but insurers typically use proprietary models that go beyond public maps. Still, living in a high-designation zone can impact availability and cost.
Can I change my risk designation? In most cases, no. Maps reflect area-wide environmental modeling. Individual mitigation usually does not change the zone label, though it can influence loss probability.
Does defensible space matter if the map category stays the same? Yes. While it may not change the classification, it directly affects how your home performs during ember exposure.