How to Read Your Wildfire Risk Map by Address
Learn how to use a wildfire risk map by address to understand your home's fire hazard rating, insurance impact, and steps to protect your property.
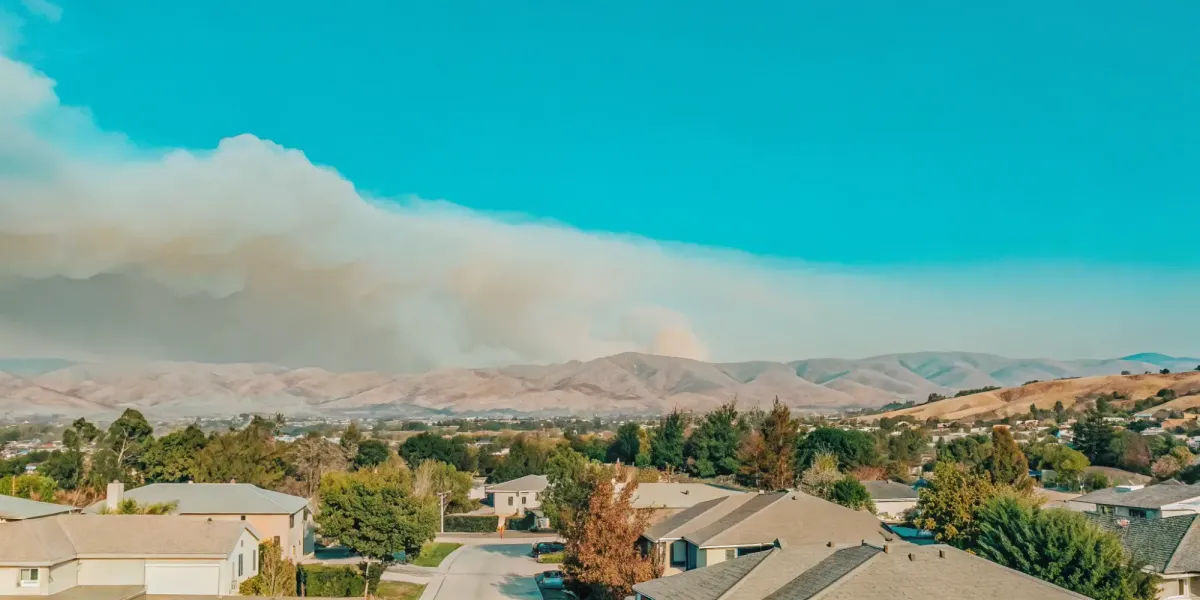
Have you ever wondered what your insurance company sees when they look at your property? It’s not just your claims history; it’s a data-driven assessment of your home’s vulnerability to wildfire. This assessment starts with your location on an official hazard map. This rating has a direct impact on your premiums and eligibility, but it’s not a destiny you have to accept. You can access the same information they use with a wildfire risk map by address. In this post, I’ll explain how to find your rating, what the different levels mean, and how you can start making your home a better risk in their eyes.
Pay Less for Home Insurance
and Avoid Non-Renewal?
Our partner, Five Bays Insurance Agency, offers a free policy checkup that spots hidden discounts to make sure you’re not paying more than you should.
Key Takeaways
- Your Wildfire Map is Your Starting Point: Use free, official tools to find your home's Fire Hazard Severity Zone. This rating is the baseline that insurers use, and knowing it gives you the power to create a targeted safety plan.
- Distinguish Between Hazard and Risk: Your map shows the area's baseline fire hazard, but your home's actual risk is something you can control. Proactive steps like creating defensible space and hardening your home directly lower the likelihood of damage, regardless of your zone.
- Connect Action to Insurability: Taking concrete steps to reduce your wildfire risk is the most effective way to stay insurable. Document your work—from clearing brush to installing fire-resistant vents—to prove to your insurer that you are actively managing your property.
Why Your Home's Wildfire Risk Map Matters
Understanding your home's specific location on a wildfire risk map is the first step toward protecting your family and property. These maps aren't just abstract illustrations; they are detailed, data-driven tools that assign a fire hazard rating directly to your address. This rating has real-world consequences, influencing everything from your home insurance eligibility and premiums to the specific safety regulations you need to follow.
Insurance companies rely heavily on these maps to determine the level of risk they are taking on with your policy. A home in a "Very High" Fire Hazard Severity Zone will face far more scrutiny—and higher costs—than one in a "Moderate" zone. Likewise, local fire departments and city planners use this information to develop community protection plans, allocate resources, and establish building codes. For you, the homeowner, knowing your zone is empowering. It gives you a clear starting point for taking meaningful action, helping you prioritize the most effective home hardening and defensible space projects to lower your risk and stay insurable.
How Are Wildfire Risk Maps Made?
Official wildfire maps, like California's Fire Hazard Severity Zones (FHSZ), are created using extensive scientific analysis. They aren't arbitrary lines drawn on a map; they are the result of models that evaluate the specific factors that cause wildfires to start and spread. These models consider the landscape's physical and environmental conditions, including the type and density of vegetation that acts as fuel, the steepness of the terrain, and typical weather patterns like wind and low humidity. They also incorporate data on how far burning embers can travel and the area's fire history. By combining these elements, experts can map out which areas are most likely to experience severe wildfires.
Why Your Address Is Key for Insurance and Safety
Your property's specific location on a hazard map is the critical piece of information that insurers, lenders, and local agencies use to make decisions. When an insurance underwriter assesses your application, they will look up your address to see which zone it falls into. This rating directly impacts your ability to get or keep coverage and what you will pay for it. These maps are also a primary tool for community-wide safety planning. They help officials identify areas that need stronger building codes, more aggressive vegetation management, or improved evacuation routes. You can look up your own property on these publicly available maps to understand exactly what officials and insurers see when they look at your home.
Hazard vs. Risk: What's the Difference?
It’s important to understand that these maps show fire hazard, not necessarily your individual risk. Think of "hazard" as the baseline potential for a wildfire based on natural conditions you can't change, like climate and topography. It reflects how a fire might behave in your general area over the next 30 to 50 years, without considering any safety measures. "Risk," on the other hand, is the actual likelihood of your home sustaining damage, and it's something you have control over. By taking proactive steps like clearing defensible space and hardening your home with fire-resistant materials, you can significantly lower your risk, even if you live in a high-hazard zone. This distinction is key, because it shows that you can create a tailored plan to make your property more resilient.
How to Find Your Home's Wildfire Risk
Understanding your property's specific wildfire risk is the first step toward protecting your home and your finances. If you've faced a non-renewal notice or a shocking premium increase, your home's official risk rating is almost certainly the reason why. This isn’t some secret score; it’s public information based on factors like vegetation, weather patterns, and topography. By looking up your address, you can see exactly what your insurer sees, giving you a clear starting point for action.
This knowledge is power. It allows you to move from a place of frustration to one of focused strategy. Instead of guessing which home improvements matter, you can align your efforts with your specific risk level. It also equips you to have more productive conversations with your insurance agent about potential mitigation credits that could lower your premium. Knowing your risk level is the foundational piece of information you need to build an effective Wildfire Action Plan and take back control of your family's safety and financial stability. Fortunately, several free and reliable tools, often managed by state and federal agencies, can help you find your rating in just a few minutes.
Key Tools for Looking Up Your Address
Several official sources can give you a clear picture of your property’s wildfire risk. For California residents, the most important resource is the official Fire Hazard Severity Zone maps from the Office of the State Fire Marshal. These maps classify areas based on the likelihood and intensity of a potential wildfire. Another excellent state-level tool is MyHazards, which shows a range of local risks, including fire. On a national level, the U.S. Forest Service offers a user-friendly website called Wildfire Risk to Communities. It provides a detailed breakdown of your community’s risk profile, helping you understand how wildfire could impact your neighborhood and its resources.
A Step-by-Step Guide to Finding Your Risk Rating
Using these tools is straightforward. To check your Fire Hazard Severity Zone (FHSZ), visit the state fire marshal’s website and enter your address into the map viewer. The map will show your property and its color-coded zone, which corresponds to a specific risk level. Similarly, the MyHazards and Wildfire Risk to Communities websites work like a search engine—just type in your address to get a report. For real-time information on active fires, you can use the wildfires layer in Google Maps to see current fire perimeters and safety alerts. Taking a few minutes to look up your address on these platforms gives you the essential information you need to start making a plan.
What Do the Wildfire Risk Levels Mean for You?
Once you’ve found your property on a wildfire risk map, the next step is understanding what that rating actually means for your home, your insurance, and your safety. Your zone isn’t just a label; it’s a guide that helps you prioritize your preparedness efforts. It tells you what regulations you need to follow and gives you a clear picture of the threat you’re facing. This knowledge is crucial because it allows you to have more productive conversations with your insurance provider and, most importantly, take the right steps to protect your family and property. Think of your risk level as the starting point for your action plan.
What Are Fire Hazard Severity Zones?
In California, the official maps used to designate wildfire threat are called Fire Hazard Severity Zones, or FHSZ. These are not just general guides; they are official maps created by CAL FIRE that show how likely and intense a wildfire could be in a specific area. To create these zones, experts analyze a combination of factors, including local vegetation, typical weather patterns, topography, and historical fire data. For homeowners, knowing your FHSZ is the first step in understanding your legal responsibilities for fire prevention, as these zones are used to set local building codes and fire safety regulations that may apply to your property.
Decoding the Risk Levels: Low, Moderate, High, and Very High
Official FHSZ maps categorize land into three primary zones of concern: Moderate, High, and Very High. While some maps might include "Low" risk, state regulations and insurance concerns are mainly focused on the higher-threat areas. A "Moderate" zone indicates a tangible fire risk, but one that is less severe than in other places. "High" and "Very High" zones represent the greatest risk, where conditions are most favorable for large, destructive wildfires. If your home is in a High or Very High zone, it’s a clear signal that you need to be especially proactive about creating defensible space and hardening your home against embers.
How Your Risk Level Affects Your Insurance
While your FHSZ designation doesn't automatically set your insurance premium, it is a major factor that insurers consider when assessing your property's risk. A home in a Very High FHSZ is seen as more likely to be damaged in a wildfire, which can lead to higher premiums, stricter coverage requirements, or even a non-renewal notice. The California Office of the State Fire Marshal clarifies that these maps don't directly change your rates, but they provide critical data for risk assessment. Understanding your zone helps you anticipate these challenges and have a more informed conversation with your insurance agent about what mitigation efforts could help you maintain or find coverage.
Defensible Space Rules for Your Zone
If you live in a High or Very High Fire Hazard Severity Zone, state law requires you to maintain defensible space around your home. This is one of the most effective ways to protect your property. According to resources like Cal MyHazards, this involves creating different zones of protection. The first five feet around your house should be an "ember-resistant zone," clear of all flammable plants, mulch, and debris. From five to 30 feet, you must remove dead vegetation and create space between trees and shrubs. Beyond that, in the "reduced fuel zone" (30 to 100 feet), you should thin out vegetation to slow the spread of fire. Following these rules isn't just about compliance—it gives firefighters a chance to defend your home.
What Factors Determine Your Wildfire Risk?
Wildfire risk maps aren't drawn up at random. They are the result of careful, scientific analysis of the environment surrounding your home. When you look up your address, the rating you see is based on a combination of factors that fire scientists have studied for decades. Understanding these core elements helps you see your property through the eyes of a fire official or an insurance underwriter. It’s the first step toward taking meaningful action to protect what matters most.
Vegetation and Fuel Load
In the world of wildfire, "fuel" is anything that can burn—and the landscape around your home is full of it. The type, amount, and condition of vegetation are primary drivers of fire risk. As state fire officials explain, "The density and arrangement of these plants can determine how easily a fire can ignite and spread." A dense thicket of dry chaparral, a forest floor covered in pine needles, or even overgrown ornamental shrubs in your yard all contribute to the local "fuel load." The more fuel there is and the closer it is to your home, the higher the risk.
Topography and Weather Patterns
The shape of the land plays a huge role in how a fire behaves. Fire spreads much faster uphill, as heat rises and preheats the fuel above it. Steep canyons and ravines can create a chimney effect, funneling flames and causing extreme fire behavior. This is why a home at the top of a slope is often at greater risk than one on flat ground. When you combine challenging topography with typical fire weather—hot, dry, and windy days—the danger multiplies. These factors are critical in determining an area’s overall risk profile and are used to create official Fire Hazard Severity Zones.
Fire History and Nearby Development
Past events are often a good predictor of future risk. Fire is a natural part of many California ecosystems, and areas that have burned before are likely to burn again. State agencies use historical fire data to identify recurring patterns and vulnerable locations. At the same time, the presence of homes and infrastructure changes the equation. The more development pushes into what’s known as the Wildland-Urban Interface (WUI), the greater the chance of a fire starting and threatening communities. Official state hazard maps account for both historical fire activity and the proximity of development when assigning risk levels.
How to Read Your Wildfire Risk Map (and What to Do Next)
Once you’ve located your property on a wildfire risk map, you have a powerful starting point for taking action. But a color-coded zone on a map doesn’t tell the whole story. Understanding what the data means—and its limitations—is the key to making smart decisions that protect your home and family. This is where you translate information into a concrete plan that can make a real difference for your insurance eligibility and your safety during a fire.
It’s easy to feel overwhelmed by a "High" or "Very High" risk rating, but that rating is not your destiny. It's a call to action. The next steps involve digging into the details of your zone, creating a specific plan for your property, and knowing when to call in an expert for a more detailed assessment. Your risk level will guide your priorities, from landscaping changes to home upgrades. Think of your risk map as a roadmap: it shows you where you are, but you still need to chart the course to get where you want to go—a safer, more resilient home that insurers see as a better risk.
Understand the Map Data and Its Limits
It’s crucial to know that official Fire Hazard Severity Zones (FHSZ) maps show hazard, not risk. Hazard is the potential for a wildfire based on factors like vegetation, topography, and weather over a 30- to 50-year period. It doesn’t account for any mitigation work you’ve done. So, even if you’ve installed a fire-resistant roof and cleared brush, the map won’t reflect that.
Think of the map as a baseline assessment of your neighborhood’s natural fire potential. It’s an essential tool for understanding the underlying conditions you’re dealing with. But your actual risk depends on your home’s specific vulnerabilities and the proactive steps you take to reduce them.
When Do Maps Get Updated?
Wildfire science is constantly evolving, and so are the maps. CAL FIRE released the first major update to its Fire Hazard Severity Zone maps since 2007, with new maps becoming official on April 1, 2024. Additional maps for Local Responsibility Areas (LRAs) are expected to be released in phases through 2025.
Because the data can change, you can’t rely on a risk assessment you saw years ago. If you haven’t checked your property’s status recently, now is the time. Insurers and local agencies will be using these new Fire Hazard Severity Zone (FHSZ) maps to inform their decisions, and you should, too. Staying current ensures your preparedness plan is based on the most accurate information available.
Create a Defensible Space Plan for Your Risk Level
Your risk level directly determines your action plan. If your home is in a High or Very High Fire Hazard Severity Zone, creating defensible space is not just a good idea—it’s often required by law and is one of the most effective ways to protect your property. This means creating a buffer between your home and the surrounding vegetation.
Start by clearing all flammable materials, from dead leaves to dry brush, within 30 feet of your house (Zone 1). From 30 to 100 feet out (Zone 2), focus on reducing fuel by thinning out trees and removing lower branches. A clear, well-maintained defensible space can slow a fire’s spread and give firefighters a safe area to defend your home.
When to Get a Professional Risk Assessment
While maps give you a great overview, they can’t capture every detail of your property. If you’ve reviewed the maps and still feel unsure, or if your property has unique features like a steep slope or unusual vegetation, it may be time for a professional assessment. An expert can provide a tailored evaluation that goes beyond the broad strokes of a hazard map.
For general questions, you can contact CAL FIRE directly. But for a personalized strategy that turns your assessment into a clear, step-by-step guide, you need a dedicated tool. The Wildfire Action Plan is designed to help you build that custom plan, ensuring you take the most effective steps to protect what matters most.
How to Lower Your Wildfire Risk and Stay Insurable
Knowing your risk level is the first step. The next, and most important, is taking action. Reducing your home’s vulnerability not only makes it safer during a wildfire but can also be the key to keeping your insurance coverage in a tough market. Insurers are increasingly looking for homeowners who are actively managing their property’s risk. When you take concrete steps to mitigate fire danger, you demonstrate that your home is a more defensible, lower-risk investment for them. This proactive approach can be the deciding factor that helps you maintain your policy, find new coverage, or even qualify for discounts that make your premium more affordable.
The good news is that many of the most effective actions are entirely within your control. You don't have to be a fire expert to make a significant impact. From simple landscaping changes you can do over a weekend to planning for long-term home improvements, every step you take builds a stronger defense against wildfire. These actions also strengthen your position with insurance carriers, giving you more control over your financial future. Let’s walk through the most important actions you can take to protect your home and stay insurable.
Harden Your Home and Landscape
Think of your property as having two layers of defense. The first is creating a "defensible space" by clearing flammable materials like dead plants, dry leaves, and woodpiles away from your house. This buffer zone can stop a ground fire from reaching your home. The second layer is “hardening” your home itself. This means using fire-resistant materials for your roof, siding, and vents to protect it from flying embers, which are a primary cause of home ignition during a wildfire. These actions make your home a much tougher target for fire, significantly increasing its chances of survival. You can find detailed guidance on creating a defensible space from CAL FIRE.
Prepare Your Evacuation Plan
When a wildfire threatens your community, having a clear plan can make all the difference. A well-prepared evacuation plan ensures you and your family can get to safety quickly and calmly, without having to make critical decisions under stress. Your plan should include multiple escape routes, a designated meeting place, and a “go bag” for each family member with essentials like water, medications, and important documents. Knowing what to do and where to go saves precious time and, most importantly, saves lives. A personalized Wildfire Action Plan can help you organize all these details in one place, so you’re ready before an emergency strikes.
Document Your Work for Insurance Credits
If you’ve invested time and money into reducing your wildfire risk, make sure you get credit for it. Keep a detailed record of all your mitigation efforts. Take before-and-after photos of your defensible space, save receipts for fire-resistant building materials, and get certifications for any professional work done. When you speak with your insurance agent, present this portfolio as proof of your proactive risk reduction. While risk maps don’t directly set your rates, this documentation can be a powerful tool in negotiating your premium or preventing a non-renewal. It shows you are a responsible homeowner committed to protecting your property.
Plan for Long-Term Property Improvements
While immediate actions are crucial, it’s also smart to plan for the future. When it’s time to replace your roof, upgrade your windows, or remodel your deck, choose fire-resistant materials. New building codes in high-risk areas often mandate these features for a reason—they are proven to work. Integrating home hardening into your long-term maintenance and improvement plans is a strategic investment in your property’s safety and value. It not only makes your home more resilient but also ensures it meets modern safety standards, which is increasingly important for maintaining insurability in wildfire-prone regions.
Related Articles
Pay Less for Home Insurance
and Avoid Non-Renewal?
Our partner, Five Bays Insurance Agency, offers a free policy checkup that spots hidden discounts to make sure you’re not paying more than you should.
Frequently Asked Questions
My insurance premium went way up (or I was non-renewed), but my neighborhood hasn't changed. Why? Insurers are relying more heavily on new, highly detailed data from official state maps. These maps analyze the long-term fire potential of the landscape itself—the vegetation, slopes, and weather patterns. So, while your street may look the same, the underlying hazard assessment for your entire area has likely become more precise, leading carriers to re-evaluate their risk.
Can I change my property's official Fire Hazard Severity Zone rating? You cannot change the official hazard rating for your zone, as it's based on broad environmental factors like topography and climate that are beyond your control. However, you absolutely can change your home's individual risk. By creating defensible space and hardening your home with fire-resistant materials, you lower the actual likelihood of damage, making your property a much safer bet than the general zone rating might suggest.
What's the most important first step if I find out I'm in a "High" or "Very High" risk zone? Start with the area immediately surrounding your home. State law and fire science both point to the first five feet from your foundation as the most critical space to manage. This "ember-resistant zone" should be completely free of flammable materials—that means clearing away bark mulch, dead leaves, and overgrown shrubs. This single action dramatically reduces the chance of wind-blown embers igniting your house.
Will hardening my home and creating defensible space guarantee I can keep my insurance? While there are no guarantees in today's challenging insurance market, taking these steps is the single most effective strategy for improving your chances. Proactively reducing your risk and documenting your work with photos and receipts gives you concrete proof to show that your home is a lower risk than others in the same hazard zone. This can be a powerful factor in an insurer's decision to offer or renew a policy.
The official map shows my whole neighborhood is high-hazard. Does that mean my home is doomed in a wildfire? Absolutely not. A high-hazard rating means the surrounding environment has the potential for a severe wildfire, but it doesn't determine your home's fate. Your property's survival is overwhelmingly influenced by the condition of the structure itself and the 100 feet of defensible space around it. A well-prepared home can absolutely survive a wildfire, even when others nearby do not.